Archive

August 2026

Browsing

Scotiabank stock price continued its strong bull run this week, reaching an all-time high. BNS has jumped 30% this year and 68% over the past 12 months, outpacing the SPDR S&P Bank ETF (KBE), which has risen just 16% this year. This rally may continue in the foreseeable future, as the bank’s revenue growth is gaining momentum despite ongoing US-Canada trade tensions.

Scotiabank stock has jumped as revenue growth continues

Bank of Scotiabank is the fourth-largest Canadian bank by assets after Royal Bank of Canada, Toronto-Dominion Bank, and Bank of Montreal. Its financial results showed that its business is doing well, helped by its wealth management business.

The company’s net income jumped to C$2.9 billion in the third quarter from C$2.52 billion in the same period last year. Its profitability also continued rising, with its earnings per share rising to C$2.22. In a statement, Scott Thomson, the CEO, said:

“In particular, we exceeded our 14% return on equity target this quarter, highlighting the improvements that we have made across the bank to increase margins and fee income.”

The biggest driver for the its revenue was the its wealth management segment, which made C$518 million, up by 23% from the same period last year. Its banking and markets segment made $647 million, also 37% higher than what it made last year. 

Bank of Nova Scotia’s Canadian banking and international segments made C$1.07 billion and C$766 million, respectively. These two segments rose by 12% and 8%, respectively. 

The company continues to return funds to its investors, which has helped to boost its earnings-per-share. It repurchased 8.6 million shares in the last quarter, bringing its total repurchases and dividends to C$6.3 billion. It now has a dividend yield of about 3.5%, even as its stock remains at a record high.

A potential catalyst for the stock is that President Donald Trump will likely TACO on his ongoing trade war with Canada. Such a move will reduce the ongoing tensions between the two countries, which are some of the biggest trading partners in the world.

Still, there is a risk that Bank of Nova Scotia is relatively overvalued, with its forward price-to-earnings ratio of 15, higher than its American peers like Goldman Sachs and JPMorgan Chase.

Bank of Nova Scotia stock price analysis

BNS stock chart | Source: TradingView

The daily chart shows that the Scotiabank share price has been in a strong upward trend this year. It rose above the crucial resistance level of $127.58, its highest point in July and August this year. A move above that level invalidated the double-top pattern, which is a common bearish reversal sign.

The stock has remained steady above the 100-day Exponential Moving Average (EMA), while the Relative Strength Index (RSI) moved above the neutral level of 50. Therefore, the stock will likely continue the bullish momentum, potentially to the psychological level of C$150.

The post Scotiabank stock has soared to a record high after earnings: more upside? appeared first on Invezz
Even as Wall Street’s broader conviction on artificial intelligence holds firm, short-term positioning fatigue is threatening to unwind the market’s most lucrative trade.

Chip stocks face a sharp near-term drawdown risk, driven less by any operational stumble than by overcrowded portfolio bets colliding with macroeconomic pressure.

Bank of America semiconductor analyst Vivek Arya thinks the PHLX Semiconductor Index has another 10% of downside in it, a call he laid out for clients Monday.

A drop of that size would extend a two-month slide across the sector and pull valuation multiples back to levels last seen before ChatGPT’s 2022 launch.

BofA favours caution on chip stocks in the near-term

The projected pullback reflects a sector straining under heavy institutional weight as much as any deterioration in fundamentals.

Chip stocks sit 13% overweight relative to the S&P 500 – leaving the group exposed to forced selling the moment sentiment turns.

Beyond crowded positioning, Arya pointed to compounding pressures, elevated interest rates, emerging data-center backlash, and complex circular financing arrangements among AI infrastructure players that together could complete a valuation reset already underway.

Both indexes now trade near 20x forward earnings, a parity that erases years of valuation whiplash: chip multiples swung from a 9% discount to the S&P 500 before ChatGPT’s debut to a 15% premium at the height of the AI trade, before recent declines closed the gap.

Arya recommends buying chip stocks on further pullback

Despite flagging near-term downside, the Bank of America analyst recommends treating any further decline as an entry point rather than a warning sign.

Why? Because companies within the semiconductor index are expanding forward earnings per share (EPS) at a compound annual growth rate of roughly 70%.

Measured against that pace of growth, the analyst called the current 20x forward multiple “cheap,” adding that seasonal trading patterns have historically turned bullish heading into year-end.

On that basis, the firm assigned “enhanced buy” ratings to eight names: Nvidia (NVDA), Marvell, Micron, Lam Research, AMD, Intel, Analog Devices, and ON Semiconductor.

Catalysts are already in motion: Marvell is accelerating its custom AI chip rollout, while Nvidia reports quarterly results after Wednesday’s close, with BofA flagging risk from slowing capital-return plans and uneven enterprise demand.

What to look for moving forward?

The tension between crowded short-term positioning and durable secular earnings growth sets up a pivotal test heading into Nvidia’s report tonight.

A pullback tied to softer capital-return guidance could trigger further momentum selling in the immediate session, yet the return of chip valuations to historical parity has already wrung out much of the speculative excess.

From here, execution on custom silicon programs is likely to separate winners from laggards, with specialized suppliers such as Marvell positioned to gain share even as enterprise spending stays uneven.

Rather than signaling a structural break in AI capital expenditure, a further 10% reset would simply realign stock multiples with underlying earnings growth, clearing the runway for a rebound into year-end.

The post BofA warns of another 10% decline in chip stocks appeared first on Invezz

The post Thailand SEC Proposes Bitcoin, ETH ETF Rules appeared first on Coinpedia Fintech News

Thailand’s Securities and Exchange Commission opened a public comment period on Monday for draft regulations covering crypto exchange-traded funds, marking a formal step toward introducing regulated Bitcoin and Ethereum ETF products in the country. The proposal covers two areas. A regulatory framework for establishing crypto ETFs in Thailand, and revised qualification standards for foreign custodians …

The post Banks Unveil ‘BankChain’ Alliance to Rival Stablecoins Amid CLARITY Act Holdup appeared first on Coinpedia Fintech News

39 banking associations in the United States have jointly formed the “BankChain Alliance” to curb their fears of client and capital flight into blockchain-based stablecoins. Banks compete with stablecoins via on-chain banking Initiated by the Texas Banking Association, the consortium represents thousands of community and mid-sized commercial banks looking to develop a 24/7, nationwide, bank-governed …

The post Bitmine Nears 5% ETH Goal: Can Ethereum Price Rally to $3,000? appeared first on Coinpedia Fintech News

Bitmine is making another aggressive bet on Ethereum, with fresh on-chain activity suggesting the company is getting closer to its goal of owning 5% of the entire ETH supply. The buying comes as Ethereum has gained more than 30% in a week, while analysts point to stronger fundamentals and a possible shift in ETH’s market …

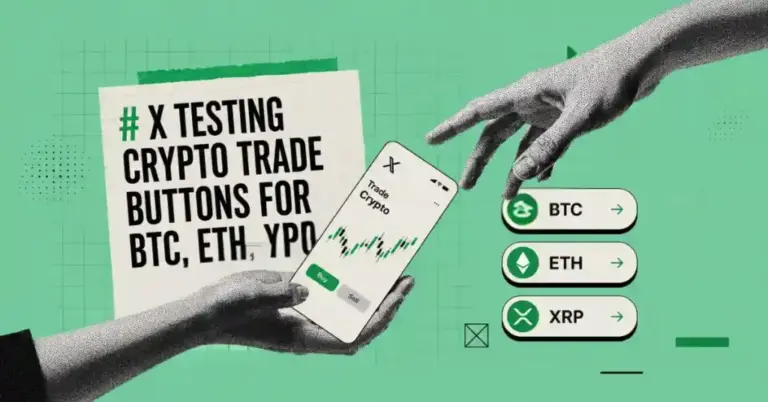
The post X Testing Crypto Trade Buttons for BTC, ETH, XRP and More appeared first on Coinpedia Fintech News

X may soon let users trade crypto directly from charts inside posts. Former X product head Nikita Bier said trade buttons could be added to crypto charts, although the feature is still being tested and there’s no confirmed launch date yet. It could support coins like BTC, ETH, SOL, XRP, ZEC and XLM, building on …

The post Here’s When and How Bitcoin Price Will Hit $100K appeared first on Coinpedia Fintech News

Bitcoin (BTC) has made a strong recovery after the recent $5 billion short squeeze, but Charles Edwards, founder of Capriole Investments in an interview with John Gillen said the next big move for BTC will depend on what happens with U.S. policy, the Federal Reserve and institutional demand. He remains positioned long, yet sees $70,000 …

Intuit shares fell about 11% in premarket trading on Wednesday after the enterprise software company on Tuesday issued a weaker-than-expected revenue outlook for fiscal 2027, warning that efforts to increase customer growth and market share will weigh on near-term sales.

The decline came despite Intuit beating Wall Street expectations for both fourth-quarter revenue and earnings.

The company forecast fiscal 2027 revenue of $23.28 billion to $23.51 billion, representing growth of 9% to 10%.

That would mark a slowdown from the 14% revenue growth recorded in fiscal 2026 and fall below analysts’ estimate of $23.72 billion, according to LSEG-compiled data.

Intuit attributed the slower outlook to weaker sales at Mailchimp, continued declines in its desktop products and lower average revenue per TurboTax customer following changes intended to attract more users.

“Looking ahead, we’re focused on scaling our Big Bets, accelerating customer growth, and making deliberate choices to create a stronger foundation for durable long-term growth,” CEO Sasan Goodarzi said.

For the fourth quarter, revenue increased 13.6% to $4.35 billion, beating the $4.27 billion expected by analysts.

Intuit expects fiscal 2027 adjusted earnings per share of $22.88 to $23.12, including a $5.81 impact from share-based compensation expense.

Analysts had been expecting $27.32.

The company also forecast first-quarter revenue of $4.29 billion to $4.31 billion, below the $4.36 billion analyst estimate.

Like many software companies, Intuit has come under pressure in recent months, with its shares falling from a record high of $812 in July last year to now trading at levels of $357.

The shares are down 43% this year.

The decline has been driven largely by investor concerns that the rise of AI-powered tools could disrupt the company’s business.

TurboTax strategy shifts toward customer growth

A key part of Intuit’s new strategy involves accepting lower revenue from individual TurboTax users in exchange for expanding its customer base.

The company said it lost “quality DIY customers to low-cost providers” during the latest tax season as consumers gained access to a growing number of cheaper alternatives.

“Price is now the number 1 reason customers leave TurboTax,” Goodarzi said on the company’s earnings call on Tuesday.

Historically, Intuit focused its TurboTax strategy on maximizing tax revenue and average revenue per customer by moving users toward higher-value products.

The company is now changing that approach, prioritizing customer acquisition and retention.

“This means we are deliberately accepting lower initial DIY tax ARPC to acquire and retain more quality customers, grow e-file share and create greater lifetime value,” Goodarzi said.

Chief Financial Officer Sandeep Aujla said the fiscal 2027 outlook reflects “deliberate actions” to improve the price-value equation for DIY customers, resulting in lower tax ARPC.

Intuit expects TurboTax revenue to grow only 2% to 3% in fiscal 2027, compared with 7% growth in fiscal 2026.

QuickBooks also moves toward lower prices

The company is applying a similar strategy to QuickBooks, where it is introducing free and lower-cost products to bring more small businesses into its ecosystem.

Intuit said QuickBooks Free and QuickBooks Lite are designed to widen the customer funnel, with the company expecting to monetize users through payments adoption and eventual upgrades to paid products.

QuickBooks Free had more than 20,000 customers either actively using the product or converting to paid offerings as of last month, according to Intuit.

The approach represents a broader shift from maximizing revenue from existing customers toward building a larger base that could generate greater lifetime value over time.

However, investors are being asked to accept slower near-term growth while Intuit tests whether the strategy can translate into stronger customer acquisition and retention.

Analysts split over Intuit’s prospects

Jefferies maintained a Buy rating and $500 price target, arguing that the conservative outlook creates a relatively low bar for Intuit to clear.

The firm noted that fiscal 2027 revenue growth of 9% to 10% would represent a decline of more than 400 basis points from fiscal 2026 and mark the first time since fiscal 2015 that Intuit’s growth could fall below 10%.

Jefferies also pointed to the weakness in TurboTax guidance.

Its 2% to 3% growth forecast is below H&R Block’s 4.8% outlook, while TurboTax revenue has not grown below roughly 7% over the past 11 fiscal years.

Morgan Stanley took a more cautious stance, cutting its price target to $315 from $335 while retaining an Equalweight rating.

The firm said execution risk remains high until the company demonstrates that its pricing reset can successfully drive customer growth.

Morgan Stanley nevertheless noted that Intuit appears inexpensive at roughly 14 times calendar 2027 earnings.

Mizuho retained its Outperform rating and $430 price target.

AI remains a key part of the investment case

Intuit’s earnings also offered evidence that artificial intelligence is supporting rather than replacing parts of its business.

“The fourth quarter “backs up Intuit’s argument that AI is expanding its ‌business ⁠rather than hollowing it out, yet the slower growth guide suggests the company itself isn’t promising the acceleration continues at the same pace,” said Gadjo Sevilla, analyst at Emarketer.

Intuit shares are now down about 43% this year, leaving investors to weigh the company’s lower valuation against the uncertainty surrounding its growth strategy.

The central question is whether accepting lower revenue per customer today can generate enough additional users, market share and lifetime value to restore growth over the longer term.

The post Intuit stock plunges after weak 2027 revenue outlook: Is it a buy? appeared first on Invezz

XRP slipped below $1.50 on Wednesday as traders took profits after a rapid cryptocurrency rally.

The token traded around $1.44-$1.48 after surging from roughly $1 to as high as $1.70 in less than a week, a gain of about 70% at the peak.

The reversal raised questions over whether the rally moved too quickly or exposed weaker spot demand.

$1.70 brought sellers back after a furious rally

XRP’s advance carried it into the $1.50-$1.70 region, an area TradingKey identified as a zone of previous peaks and concentrated trading volume.

That matters because investors trapped during earlier rallies were given another opportunity to exit, while short-term traders were sitting on large gains.

Bitcoin’s retreat after moving above $80,000 and elevated Bitcoin dominance also drained liquidity from altcoins.

FX Leaders analyst Arslan Ali Butt said consolidation after a roughly 72% advance was normal.

He identified $1.4287 as immediate support and $1.5328 as the level XRP needs to clear for “stronger momentum” towards another test of $1.70.

The setup is therefore less complicated than Wednesday’s drop might suggest.

XRP did not encounter a sudden deterioration in its fundamental story near $1.70. It reached a heavily traded resistance area after compressing months of potential gains into a few days, giving investors a strong incentive to take money off the table.

Leverage turned from fuel into a problem

The larger concern for bulls is how much of the rally was being amplified by derivatives.

CryptoQuant data cited by CCN showed Binance’s estimated XRP leverage ratio at its highest level in more than seven months.

CryptoQuant contributor Arab Chain said rising leverage alongside higher prices and open interest “could reflect increased confidence” and potentially support further gains.

That dynamic worked while XRP was climbing. Once the token stalled, the same leverage increased downside pressure.

CCN reported XRP futures open interest near $3.45 billion, with roughly two Binance accounts positioned long for every one short. Among top traders, the imbalance was closer to three-to-one.

About $18.9 million of XRP positions were liquidated over 24 hours, including roughly $15 million in longs. Futures generated about $6.4 billion in trading volume, versus around $1.2 billion in spot volume.

That imbalance helps explain the reversal.

ETF buying keeps the broader bull case alive

The correction is occurring despite evidence that regulated demand remains constructive.

FX Leaders reported that US-listed XRP products have recorded positive inflows for six consecutive weeks, including roughly $40 million in the latest week.

That matters because spot-based investment demand is generally more durable than leveraged futures positioning, while activity across crypto exchanges can be more sensitive to short-term shifts in sentiment and leverage.

Sustained ETF inflows could therefore help absorb some of the profit-taking pressure.

But bulls still need to regain control of key levels.

Butt sees $1.4287 as immediate support. Holding it keeps the short-term structure constructive, while a move above $1.5328 could reopen the path towards $1.70. A break lower could expose the $1.34-$1.35 region.

The post XRP loses $1.50 after explosive rally: why are traders taking profits now? appeared first on Invezz

Micron stock has slumped sharply in the past few months, falling from the year-to-date high of $1,257 in June to the current $932. This retreat has happened despite its strong performance as the AI boom gains steam. This article explores what to expect as Nvidia publishes its financial results. 

Nvidia earnings to have an impact on Micron

The most important catalyst for Micron shares will be Nvidia’s earnings report, which will provide more color about the state of the AI industry. These results will have an impact on other memory and semiconductor companies. 

Analysts are optimistic about the company, with Raymond James boosting its target to $352, implying a 65% surge from the current level. Other analysts from companies like Rosenblatt Securities, KeyCorp, and Cantor Fitzgerald expect it to jump to $300 and above. 

If Nvidia’s earnings come in strong, it will signal that the AI industry remains healthy, a positive read-through for memory names like Micron, SK Hynix, and SanDisk. Weak guidance, on the other hand, would point to headwinds building in the sector. Micron in particular is worth watching closely: as one of Nvidia’s top memory suppliers, its stock tends to move in direct response to Nvidia’s results.

On the positive side, there are signs that the sector is booming, with all companies releasing strong financial results and guidance. 

Micron earnings growth is accelerating

The most recent financial results showed that Micron’s business is booming. Its recent results showed that its revenue jumped by 74% in the quarter to $41.5 billion. This figure was a 346% increase from what it made in the same period last year. Its gross margins also continued growing.

Management’s guidance for the fiscal fourth quarter was among the company’s strongest yet, calling for revenue of $50 billion. Analysts, however, are expecting an even higher figure — $50.78 billion, a 348% jump year-over-year. Historically, the company has beaten its own guidance, and if that pattern holds, revenue could come in above $53 billion, pushing the annual total to $133 billion.

Its profits are also soaring. Its cloud memory’s operating margin jumped to 78% from 46% in the same period last year. The core data center margin rose to 83% from 20%, while the automotive one jumped to 75%. This margin will likely continue as HBM prices rise. Indeed, in a recent note, DigiTimes warned that HBM prices may double to $4 per gigabit by next year.

All this is happening at a time when the company is trading at bargain prices. Its forward price-to-earnings ratio has moved to 12.4, much lower than the technology sector median of 34. Also, the company has one of the best rule-of-40 multiples, which has now jumped to 327%.

Micron stock price technical analysis

MU stock chart | Source: TradingView

The daily chart shows that the MU stock price has held steady in the past few days, moving from a low of $737 in July to the current $932. A closer look shows that the stock has stabilized above the 50-day Exponential Moving Average (EMA). 

Most notably, the stock has formed an inverted head-and-shoulders pattern, a common bullish reversal sign in technical analysis. This pattern often leads to strong rebounds over time. 

Therefore, there is a possibility that the stock will bounce back, potentially to the key resistance level of $1,257, which is about 34% from the current level.

The post Micron stock: A bullish reversal pattern and the Nvidia earnings catalyst appeared first on Invezz