Archive

August 2026

Browsing

Rubrik stock price has had a rollercoaster this week. It jumped to a record high of $107.7 on Thursday and then pared back some of those gains after publishing its financial results. It dropped by over 7% and retested the crucial support level of $100.

Rubrik published strong earnings

Rubrik is a top company in the cybersecurity industry, where it helps companies protect, monitor, and recover their data. Its backup and recovery solutions helps companies to automatically back up and recover data from on-premises systems, cloud platforms, and databases. The company also helps in ransomware protection, data security, and cloud data protection.

Rubrik is used by some of the biggest companies in the United States, including popular names like PepsiCo, Iron Mountain, Adobe, and The Home Depot.

The company, together with others in the cybersecurity industry, is at an inflection point. For a long time, attacks have been coming from humans, and this trend will continue over time. 

Now, future attacks will mostly come from AI operators as evidenced by the recent hackings by models made by Anthropic and OpenAI. This is important because some of the most advanced models are coming from Chinese companies. As a result, its results showed that its total addressable market (TAM) will be $125 billion by 2029. In a statement, the CEO said:

“Mythos and frontier AI models have fundamentally changed the cybersecurity landscape. This new reality demands not only machine speed cyber recovery but also autonomous runtime AI agent security. Rubrik’s Agentic Cyber Resilience delivers on both to enable trusted AI transformation.”

READ MORE: Why analysts now see a 32% upside to CrowdStrike stock after its ‘best quarter’?

Rubrik’s results showed that its revenue jumped by 38% in the second quarter to $427 million. This revenue growth was better than what analysts were expecting. Also, its free cash flow (FCF) jumped to $76.8 million. This growth happened as the number of customers paying $100,000 a year crossed the 3,000 milestone.

The company also provided an encouraging guidance. It now expects that its third quarter revenue will be between $429 million and $431 million. It also expects that its annual revenue will be between $1.685 billion and $1.693 billion. Yahoo Finance data shows that analysts were expecting its annual revenue would jump to $1.64 billion, followed by $2 billion next year.

To some extent, Rubrik is a highly overvalued company since it has a market capitalization of over $22 billion and is still making losses. It has made a net loss of over $2 billion in the past few years. Indeed, its current price is in the same range as the consensus analysts forecast.

Rubrik stock technical analysis

RBRK stock chart | Source: TradingView

The daily chart shows that the RBRK stock has been in a strong bull run in the past few months, moving from a low of $42.4 in May to a record high of $107 on Thursday. It then dropped to $100 after its earnings. 

On the positive side, the stock has remained above all moving averages and has formed an inverted head-and-shoulders pattern. It has been forming a series of higher highs and higher lows. 

Therefore, the stock will likely resume the uptrend and potentially reach a high of $120. The bullish outlook will remain as long as it is above the 50-day moving average.

The post Rubrik stock drops as gross margin slips: Is the selloff a buying opportunity? appeared first on Invezz
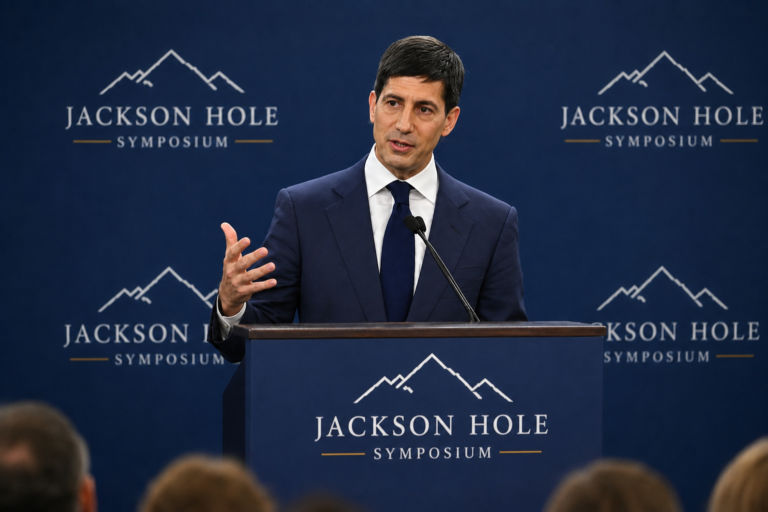
Federal Reserve Chair Kevin Warsh signaled that the US central bank may need to do more to contain inflation, arguing that recent improvements in price data have not provided enough evidence of a sustained slowdown.

In his first speech as Fed chair at the Kansas City Fed’s annual Jackson Hole symposium, Warsh said the central bank must be confident that underlying inflation is moving toward its 2% target at a sufficient pace.

Without that confidence, he said, “we have work to do.”

Warsh stopped short of saying whether he would support a rate increase at the Fed’s September meeting.

Instead, he emphasized that his approach would focus on responding to incoming data rather than signaling specific policy decisions in advance.

The comments come as policymakers remain divided over the appropriate path for interest rates.

Three Fed officials voted for a rate increase at the previous meeting, while others have indicated they could support higher rates.

https://twitter.com/InvezzPortal/status/2093347134292566398

Financial conditions remain supportive

Warsh said the current federal funds rate of 3.5%-3.75% does not appear to be placing significant restraint on the broader economy.

Credit and loan markets, he noted, show limited evidence of policy restraint.

Although he acknowledged signs of weakness in areas including housing and agriculture, Warsh said he would be “hard pressed to describe broad financial conditions as restrictive.”

His assessment could strengthen the case for maintaining a restrictive policy stance or potentially raising rates if inflation fails to make further progress toward the Fed’s target.

The debate within the central bank has centered partly on the causes of persistent inflation.

Some policymakers have viewed elevated price pressures as the result of temporary shocks, including tariffs and the Iran war. Others have argued that demand remains strong enough relative to supply to allow businesses to sustain price increases.

Warsh said he had previously favored waiting for additional information before deciding whether a change in interest-rate policy was appropriate, citing potential developments in supply chains, investment and geopolitics.

Inflation remains above Fed target

Recent inflation readings have reduced some pressure for a September rate increase. Market-implied expectations for a hike had fallen below 40% earlier this month after softer readings in June and July.

According to FedWatch data, 55.7% of participants expect a 25-basis-point hike, while 44.3% expect rates to remain unchanged. 

Warsh acknowledged that the summer inflation figures were better than expected but said they had not demonstrated a meaningful improvement in underlying trends.

He highlighted the breadth of price increases across the economy. About half of the items in the Fed’s preferred inflation basket are increasing at an annual rate above 3%, compared with roughly one-third during the two decades before the pandemic.

The Personal Consumption Expenditures price index, the Fed’s preferred inflation gauge, is currently running at 3.7%, well above the central bank’s 2% target.

Warsh also said inflation was currently more concerning for policymakers than the labor market, which he described as broadly robust.

The remarks provide the clearest indication yet of Warsh’s approach to monetary policy since taking over as Fed chair.

While he avoided committing to a specific rate decision, his emphasis on persistent inflation leaves open the possibility of further policy tightening if price pressures fail to ease sufficiently.

The post Fed Chair Kevin Warsh warns inflation may require more action appeared first on Invezz

Adobe stock continued its strong rally this week, reaching its highest level since February this year. ADBE has soared by 52% from its lowest level this year, and this rally may continue after forming a golden cross pattern as its earnings loom.

Adobe stock has formed a golden cross pattern

The daily chart shows that ADBE stock has soared in recent months, climbing from a June low of $190 to its current price of $289. The rally was driven by investors buying the dip and a broader rebound in software stocks. Adobe’s uptrend continued on Thursday, boosted by Salesforce shares surging after a strong earnings report.

Adobe has moved above the crucial resistance level of $275, its highest level on June 1, a sign that bulls have prevailed. Most importantly, it has now formed a golden cross pattern as the 50-day and 200-day Weighted Moving Averages (WMA) crossed each other. This pattern normally leads to more gains over time. 

There are also signs that the stock has formed an inverted head-and-shoulders pattern, which is a common reversal sign. This pattern is made up of a head at $190, shoulders, and a neckline at $275. 

Therefore, the most likely scenario is where the stock continues rising, with the initial target to watch being at $300. A move above that level will point to further gains, potentially to the crucial resistance level of $362, its highest level in December last year. A drop below the crucial support level of $260 will invalidate the bullish outlook.

ADBE stock chart | Source: TradingView

Adobe has become a bargain ahead of earnings

Adobe, a company that owns popular brands like Photoshop, Illustrator, InDesign, Lightroom, Acrobat, Bridge, Animate, and Behance, has come under substantial pressure in the past few years. Its stock has plunged by double digits, making it a fallen angel.

Adobe shares have pulled back as investors reacted to the ongoing SaaSPocalypse fears. This is a situation where investors are fearing that software companies will be disrupted by AI tools. Adobe’s management has denied claims that AI will disrupt its business.

The recent sell-off turned Adobe into one of the cheapest names in the stock market. Seeking Alpha data shows that the company trades at a forward price-to-earnings ratio of 11.20, much lower than the sector median of 22.90. Its five-year average was 25.

The company also has an attractive Rule of 40 metric of 50%. It is made up of a revenue growth of 11% and a free cash flow margin of 39%. A Rule of 40 metric of 40 and above is a sign that it is trading at a bargain level.

The upcoming earnings report is expected to show that its revenue grew in the last quarter. Its revenue is expected to come in at $6.7 billion, up by 11.8% from what it made in the same period last year. For the year, the company is expected to jump by 11.60% to $26 billion. 

With its stock trading at bargain levels, chances are that it will announce a big share buyback. In April, the comany announced a $25 billion authorization, which will see it continue reducing its outstanding shares. Over time, the company has reduced its outstanding shares from 472 million in 2022 to the current 399 million.

The post Adobe stock analysis: Golden cross pattern takes shape ahead of earnings appeared first on Invezz

ServiceNow stock has remained in a strong bull run this month, moving to its highest level since January this year. NOW has soared to $138, up by 70% from its lowest level this year. This rally may continue as demand for its services continues and as a golden cross pattern nears.

ServiceNow stock is set to rebound amid solid fundamentals

NOW stock has slumped in the past few months, moving from a high of $240 in January last year to a low of $81.23. This sell-off happened as more companies embraced AI tools like Claude’s Cowork and ChatGPT’s projects.

The view among investors is that some of these tools would help companies automate some of the tasks that they use ServiceNow for. At the same time, investors pointed to its large acquisitions, including Armis and Moveworks. 

It bought Armis in a $7.75 billion deal and Moveworks for $2.85 billion. These acquisitions sent a message that the company was focusing on growth through acquisitions.

ServiceNow and its proponents have argued that its business will benefit from the AI boom. AI is helping it reduce costs, and improve its offerings. For example, using ServiceNow’s AI tools, clients can improve the hiring process. Also, its AI tools can help companies in its service desks.

The most recent results showed that ServiceNow’s business was doing well, with its revenue jumped by 24% in the second quarter to $3.9 billion, with Armis contributing to this growth. Its remaining performance obligations (RPO) rose by 21% to $13.2 billion. 

Most importantly, its recently-launched ServiceNow AI crossed $1 billion in annual contract value, while its contract renewal rate rose to 98% from Q1’s 97%. This means that its business is not losing customers during the AI boom.

The revenue growth is expected to continue growing in the coming months. For example, analysts predict that its third-quarter revenue rose by 20% to $4.1 billion. Its earnings-per-share is expected to move from 0.96 to $1.03. The annual revenue is expected to jump from $13 billion last year to $16.2 billion, with Armis and Moveworks contributing to the growth.

ServiceNow stock has continued rising because of the recent earnings by other software companies that have demonstrated that there is demand for their services. This includes companies like Figma, Workday, and Salesforce.

NOW stock technical analysis: golden cross nears

ServiceNow stock chart | Source: TradingView

The daily chart shows that the ServiceNow stock has rebounded in the past few months, moving from a low of $81.2 in April to the current $138.4. It is attempting to move above the crucial resistance at $138.4, its highest level on June 1 this year. 

The stock is about to form a golden cross pattern that forms when the 50-day and 200-day Exponential Moving Averages (EMA) cross each other. The spread between these two averages has continued narrowing in the past few days. 

The Relative Strength Index (RSI) and the MACD indicators have continued rising. As such, there is a possibility that the stock will continue rising, potentially to the next key resistance level of $150. A move above that level may push it to the July 2025 high of $210.

The post Is it a golden opportunity to buy ServiceNow stock as a rare pattern nears? appeared first on Invezz

Amazon shares AMZN surged 4% on Friday after Evercore ISI raised its price target on the e-commerce and cloud computing giant to $355 from $315.16, while maintaining an Outperform rating.

The move came as analysts pointed to improving trends across Amazon’s retail, artificial intelligence and cloud businesses.

Evercore sees upside from AI-powered retail

Evercore ISI based its revised target partly on findings from its 14th Annual US Online Retail survey.

The survey found that 57% of Alexa AI users had purchased a product they were previously unaware of, providing what the firm described as evidence that agentic AI could add to Amazon’s retail business.

Amazon maintained a 92% penetration rate in the survey, down from last year’s record 95% but still 34 percentage points ahead of Walmart. Same-day delivery usage also recovered to 49%.

Prime customers using same-day delivery spent 3.1 times more than non-Prime members, marking the widest gap recorded in the survey.

Meanwhile, about 46% of respondents who had seen Amazon’s Perishable Checkout feature added fresh groceries to their carts.

Evercore set its $355 price target using a 30-times multiple of its 2028 price-to-earnings estimate and retained Amazon as a top large-cap position.

Amazon expands power supply for AI data centers

Amazon is also expanding its electricity supply in Sweden as it increases data-center capacity in the Nordic country.

The company signed long-term agreements to purchase power from four wind farms developed by Eolus AB and OX2 AB.

The projects are expected to add almost 200 megawatts of electricity to Amazon’s supply. Once fully operational, the company expects to have nearly 1 gigawatt of power supply in Sweden.

The agreements come as major technology companies increase investments in electricity capacity to support growing demand from cloud computing and AI services.

Amazon plans to add another 2 million Nvidia graphics processing units to its data-center fleet in 2027 and 2028, in addition to the 1 million GPUs it previously said would begin being installed this year.

Amazon Web Services has also announced plans to acquire DuckLabs, the Amsterdam-based company behind open-source analytical database DuckDB, to strengthen its analytics capabilities.

Analysts remain bullish on Amazon

Wall Street sentiment toward Amazon has remained positive, with 22 analysts recently revising their earnings estimates upward. The consensus price target implies 27% upside from current levels.

Citizens maintained a Market Outperform rating, citing Amazon’s logistics capabilities and AI model growth.

Rosenblatt Securities also initiated coverage with a Buy rating and a $335 price target, highlighting expected growth in Amazon Web Services.

A Motley Fool report argued that Amazon’s valuation looks attractive relative to Microsoft when its growth rate is considered.

It highlighted AWS as a key driver, noting that the cloud division accounts for 60% of Amazon’s operating income and that its operating income increased 64% year over year in the second quarter.

The post Why is Amazon stock surging 4% today appeared first on Invezz

The post Crypto Media’s Traffic Collapse Isn’t an AI Story. It’s a De-Indexing Story appeared first on Coinpedia Fintech News

The story crypto media tells itself is that AI search killed its traffic. Zero-click answers absorb the query, the reader never lands on the page, and the publisher eats the loss. It’s a clean narrative, and it’s the wrong diagnosis for most of what actually happened. ICODA’s two-year traffic analysis of 40 crypto news domains …

The post Will Bitcoin, Ethereum and XRP Prices Pump or Dump After Kevin Warsh’s Jackson Hole Speech? appeared first on Coinpedia Fintech News

Bitcoin is trading at $79,619.04, Ethereum at $2,504.89 and XRP at $1.42 as markets await Federal Reserve Chair Kevin Warsh’s debut Jackson Hole address, an event traders widely view as the catalyst for crypto’s next directional move. Current Market Snapshot Bitcoin: $79,619.04, up 2.2% over 7 days, market cap $1.6 trillion Ethereum: $2,504.89, up 4.3% …

The post Strategy Stock Surges 40% as Bitcoin Rally Lifts MSTR appeared first on Coinpedia Fintech News

Michael Saylor’s Strategy (MSTR) stock is making a strong comeback, jumping nearly 40% in one month from around $82 to $140. The rally comes as Bitcoin recovered from the $60,000 range to above $80,650, giving a major boost to one of the market’s biggest Bitcoin-linked stocks.  Strategy’s large BTC holdings have also turned earlier paper …

The post Circle Internet Group Inc. (CRCL) Stock Price Prediction 2026, 2027, 2030 – 2040 appeared first on Coinpedia Fintech News

Circle Internet Group Inc. (NYSE: CRCL) stock has entered a critical phase after falling nearly 44% from its $159.47 52-week high, but the long-term growth story remains intact. The pullback has brought CRCL stock back into focus as stablecoin adoption, USDC circulation and digital-asset payments continue to expand. With Circle building a broader financial infrastructure …

The post XMR Price Breaks $450: Is Monero on Track for $500? appeared first on Coinpedia Fintech News

Monero has extended its August rally with another decisive move higher. XMR price rose 5% and pushed above $450, breaking through a resistance zone that had capped multiple recovery attempts. The breakout gives bulls a cleaner technical setup heading toward $500, while renewed attention around Monero’s liquidity infrastructure adds weight to the broader market narrative. …