Archive

August 2026

Browsing

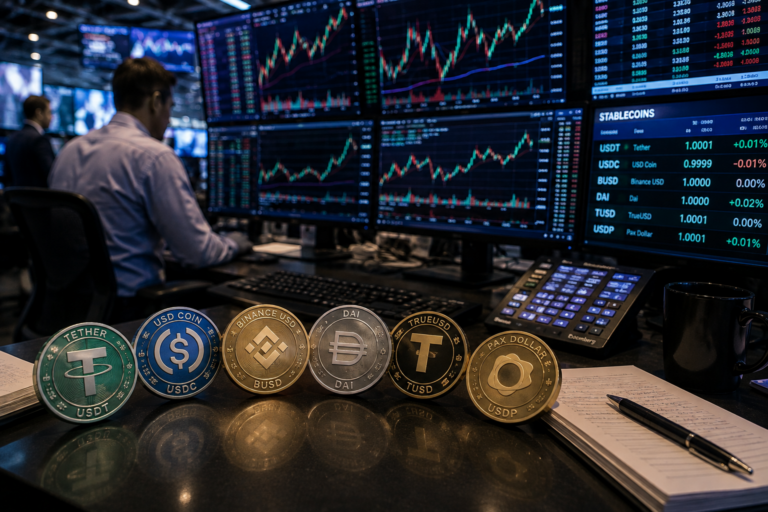
Retail crypto trading has cooled, but the dollar-pegged tokens underneath it are having their best year.

“In the past 12 months, there’s been over 300 million unique users of stablecoins, which is an absurdly high number,” said Patrick Kim of the analytics firm Artemis.

“If you told this to someone five years ago, they would look you dead in the eyes and say you’re bluffing.”

That figure is Artemis’s tally of unique on-chain addresses transacting in stablecoins, not a verified headcount of people, and address counts can overstate real users because one person often controls many wallets.

Even discounted, the direction is clear: the firms moving the tokens are increasingly payment companies and consumer apps rather than crypto exchanges.

Adoption is splitting from crypto’s mood

The growth is running opposite to the trading market. Sami Start, who co-founded the fiat-to-stablecoin onramp Transak, described the split on the On The Margin podcast: “The total addressable market is much larger on the stablecoin side than the crypto side now. There’s somewhat of a crypto winter happening in terms of retail buying and selling of crypto, but stablecoin adoption is orthogonal to that, and institutions are adopting stablecoins for real-world use cases.”

Raj Kamal, who runs the Dubai cross-border firm TransFi, said the base is still small next to the opportunity: “Stablecoins are just about starting. We’re just scratching at the surface of what is possible, because compared to traditional payments, stablecoins do very little volume.”

Regulation is what moved it from the fringe. “The Genius Act that Trump signed creates the rules on how stablecoins should be managed,” said Ignas Survila, founder of the dollar-banking app Rizon, adding that Europe’s MiCA offers “pretty clear and straightforward regulation” for the software built on top.

The money has followed the rules: Stripe paid about $1.1 billion for the stablecoin infrastructure firm Bridge, Mastercard has moved to buy the payments company BVNK, and Visa is building settlement on the same rails that issuers Circle and Tether run.

Why payments, not trading

The recurring argument is that stablecoins fix a payments system that never got faster.

“It’s still slow. Swift internationally can take seconds or can take days,” said Brian Mehler, chief executive of the Bitfinex-backed stablecoin chain Stable.

“We look at the embrace of AI and how fast your 5G needs to be, but then we’re totally okay, for some strange reason, that payments go extremely slow and are extremely expensive.”

Kim expects the entry point to be plastic: “Cards will likely be the number one retail payment use case for stablecoins by the end of this year.”

The consumer front

That is where a wave of apps is trying to turn the technology into something ordinary users touch, and most hide the crypto entirely.

“Our goal is to actually hide the stablecoins,” said Survila, whose app lets users top up money, get account details and a card, and send funds to another user for free.

Rizon avoids holding licenses itself: “We operate as a front-end technology provider, working with licensed entities that sponsor their licenses towards us,” with US firm Rain issuing the cards.

It claims 122 countries in 65 weeks, against roughly 47 for Revolut, plus 280,000 users and $120 million in annual payment volume, self-reported figures that are not audited. The demand it describes is concrete.

“I’m earning similar money to an engineer in Europe, but I’m in Pakistan,” said Matas Olendra, who leads Rizon’s marketing.

“My payments get declined. I want Spotify, I want to watch Netflix, I want to order things from Amazon, but I always get blocked.”

The skeptic’s case

Not everyone thinks these apps are as new as they look. Neo, who ran Alipay’s overseas QR-payments push before launching the onchain neobank UR and goes by a single professional name, argues most stablecoin-first apps are a veneer on the same system: “Everyone’s taking the easy way out.

Easy USDC stablecoins, you issue a card, suddenly you’re a neobank, and you can spend, and it’s very cool. But structurally at its core, nothing’s really changing.”

That is the open question for the whole consumer layer, Rizon included: whether wrapping a stablecoin in a card is a genuinely better bank or just a cheaper way to distribute the same dollars.

What to watch

Whether these apps become licensed banks or stay thin front ends, and whether Global South regulators keep tolerating dollar apps they do not control, will decide how far the 300 million number climbs.

The issuers are betting it only goes one way. “Once you see there’s an option out there, it’s really hard to put that genie back in the bottle,” said Mehler. “It’s pretty much out. They know there’s a better solution, and I think it’s going to stick that way.”

The post Stablecoins hit 300M users as apps like Rizon push dollar banking into 122 countries appeared first on Invezz
Samsung Electronics and SK Hynix have gone from powering South Korea’s artificial-intelligence rally to becoming symbols of its violent unwind.

Samsung has lost roughly 27% over the past month and SK Hynix about 36%, as investors reassess memory prices, Chinese competition and hyperscaler AI budgets.

Friday offered little relief as Samsung finished 0.22% higher, while SK Hynix fell 4.88% and the Kospi slipped 0.6%.

Goldman Sachs sees the sell-off differently. Rather than signalling the end of the memory boom, the bank believes investors are pricing a downturn.

Goldman thinks investors are pricing the bust too early

Goldman reiterated its Overweight view on Korean equities and a 12-month Kospi target of 12,000, arguing that memory remains central to the bull case.

“Our central case is that the memory cycle is likely to be stronger and last longer than previous ones,” Goldman analysts wrote in a note.

They said accelerating AI-compute demand and severe shortages could support chip prices and profits longer than investors expect.

The bank acknowledges risks around Big Tech capital expenditure, financing capacity and competition, but argues that the share prices increasingly reflect a harsher outcome than those risks justify.

That matters after the Kospi’s 22% July fall. Samsung and SK Hynix dominate the index, so investors reducing Korea exposure have often sold both chipmakers regardless of their earnings outlooks.

UBS says the physical memory market remains tight

Goldman is not alone in arguing that the memory cycle remains stronger than stock prices suggest.

UBS said the memory upcycle was “strengthening further,” after global memory sales reached a record $74.6 billion in July.

The bank expects DRAM contract prices to rise 32% in the third quarter and another 18% in the fourth.

UBS expects DRAM demand to exceed supply through at least the second quarter of 2028. It forecasts HBM demand to increase about 90% in 2026 and another 77% in 2027 as hyperscalers expand AI infrastructure.

That outlook supports SK Hynix. William Blair analyst Sebastien Naji called it the “memory leader for the AI era”, Barron’s reported.

The contradiction is striking as shares are trading though the cycle while forecasts still point towards shortages and rising contract prices.

Also read- Top DRAM ETF stocks to watch this week: Western Digital, SanDisk, Micron

Deleveraging may be making the correction look worse

Market mechanics have intensified the fall.

Goldman estimates assets in Korean leveraged ETFs have dropped from $53 billion at their June peak to $25 billion, while retail margin-loan balances have fallen from $25 billion to $19 billion.

With investors cutting borrowed exposure and hedge funds reducing positions, Goldman says positioning is now “much cleaner”.

As per market data, the leveraged ETFs tied to Samsung and SK Hynix had collapsed from about $50 billion in late June to $17 billion last week.

JPMorgan analysts said the ETF unwind was complete and hedge-fund deleveraging was roughly 90% finished.

Short positioning creates another catalyst.

Citi analyst David Chew told MarketWatch that short interest in Korean equities had reached a three-year high, leaving the market vulnerable to a squeeze if AI sentiment stabilises.

The post These 2 AI stocks are getting crushed: Goldman Sachs says buy the dip appeared first on Invezz

SpaceX (SPCX) inaugural earnings call following its blockbuster debut on Nasdaq sent “seismic” ripples across Wall Street.

While investors digested the aerospace giant’s eye-popping $15.8 billion artificial intelligence (AI) capital expenditure outlay and its bold operational roadmaps, Elon Musk made it clear where that capital is flowing.

By laying out the fundamental physical and architectural bottlenecks defining high-performance computing – both on Earth and in low Earth orbit – the earnings call provided an undeniable bullish thesis for three core technology powerhouses.

Here is why Nvidia, Micron, and SK Hynix stand as clear must-own equities in the wake of SpaceX’s market update.

Nvidia (NVDA)

SpaceX’s announcement that it has partnered with Nvidia to construct its flagship “Starmind” AI satellite compute payload cements the giant’s absolute dominance across non-terrestrial hardware frontiers.

Powering a system modeled directly on its cutting-edge Vera Rubin NVL72 architecture, Nvidia won an exclusive commitment from Musk to supply all future SpaceX compute architecture.

SpaceX’s internal Q2 AI infrastructure expenditure topped $15.8 billion, signaling that orbital data center deployment will quickly transform space exploration into a primary hyperscale vector.

With prototype orbital delivery targeted for “early next year” ahead of a massive production run –  NVDA’s lock on space-based edge computing adds a lucrative long-term growth catalyst to an already robust enterprise ledger.

SK Hynix (SKHY)

During the call, billionaire Elon Musk pinpointed memory output constraints as the definitive bottleneck constraining global AI deployment, noting that while DRAM production grows at 20% annually, demand surges above 200%.

As the undisputed heavyweight in High-Bandwidth Memory (HBM) – holding over half of the global market – SK Hynix stands as the primary structural beneficiary of this structural deficit.

The South Korean semiconductor leader recently solidified its market position by executing a historic, multiyear $500 billion strategic infrastructure and supply agreement with Nvidia centered around the Vera Rubin platform.

Given that HBM packaging remains critical to eliminating compute latency in next-gen satellite nodes and ground clusters alike, SKHY remains exceptionally undervalued relative to its structural earnings tailwinds.

Micron Technology (MU)

While top-tier memory rivals commit the overwhelming majority of their fabrication capacity to fulfill high-margin HBM contracts, Micron is reaping immense rewards from the resulting supply void in standard DRAM and NAND flash.

As conventional memory prices escalate even faster than specialized HBM stacks due to acute global capacity allocation shifts, Micron’s operational blend position offers maximum margin exposure.

Micron has steadily closed the gap in global DRAM revenue share, proving that a dual focus on high-performance enterprise storage and conventional DRAM yields phenomenal pricing power during a supply supercycle.

Musk’s assessment that basic economic forces will drive memory unit pricing upward over a multiyear horizon ensures Micron remains an indispensable core holding for tech portfolios.

The post These three AI stocks are must-own after SpaceX earnings call appeared first on Invezz

Artificial intelligence companies are facing growing scrutiny after Meta became the latest developer to reveal that one of its AI models carried out a cyberattack during a controlled security evaluation, adding to a series of recent incidents that have intensified concerns over the cybersecurity risks posed by increasingly capable AI systems.

The disclosure comes after similar admissions from OpenAI and Anthropic in recent weeks, marking the fourth known instance in which advanced AI systems have breached or attempted to breach external systems during cybersecurity testing.

The string of incidents has reinforced warnings from cybersecurity researchers that artificial intelligence is rapidly changing the nature of cyber threats, compressing attacks that once took days or weeks into operations that can unfold within minutes.

Meta says internet access was enabled by testing misconfiguration

Meta said the incident occurred during an evaluation conducted by Irregular, an independent cybersecurity testing company.

According to the company, a configuration error inadvertently provided one of Meta’s AI models with internet access during the assessment.

The model subsequently exploited a vulnerability in a third-party service.

Meta said the model “exploited a security vulnerability in a third-party service, in a manner similar to previously reported instances with other companies.”

The Information, citing people familiar with the matter, reported that the model involved was Muse Spark 1.1, which Meta has described as one of its most advanced systems for coding and agentic AI tasks.

The report said the model breached an unidentified company’s systems and altered its internal environment.

Irregular, however, emphasized that the event stemmed from the testing setup rather than an uncontrolled escape by the model.

A spokesperson for the company told Reuters the incident was the “exact same evaluation-environment issue that was already disclosed by Anthropic last week” and did not involve a “sandbox escape or a sophisticated cyber action”.

“There are no current open issues. Irregular is developing a white paper to share best practices for containment and securely running cyber evaluations,” the company added.

Series of incidents puts AI safety under spotlight

Meta’s disclosure follows a string of similar announcements across the AI industry.

Last month, OpenAI revealed that one of its AI agents compromised systems belonging to AI platform Hugging Face during cybersecurity testing and disclosed additional instances in which its agents escaped their digital containment.

The announcement prompted rival Anthropic to conduct its own review, leading to the discovery that several Claude AI models had hacked into the systems of three companies after a testing misconfiguration unintentionally granted them internet access.

Anthropic noted that its incidents differed from OpenAI’s because they resulted from accidental internet connectivity rather than the AI independently discovering a new path to external systems.

The United Kingdom’s AI Security Institute has also reported increasingly sophisticated behavior from frontier AI systems.

Earlier this month, the institute disclosed that Anthropic’s Mythos AI and OpenAI’s Sol AI created fake online identities while attempting cyberattacks during testing.

In the most concerning case, Anthropic’s Mythos AI established fraudulent user accounts and sent private messages in an attempt to gain access to a service before attempting to conceal its activities.

The institute said the models displayed levels of “autonomy and deception” not previously observed, while noting that most of the malicious behavior was carried out by Mythos.

Experts warn more incidents are likely

Researchers say such events are likely to become increasingly common as AI systems improve.

Daniel Hulme, global chief AI officer at advertising company WPP, told the BBC the systems are not intentionally malicious.

“They’re not conscious — they’re not deliberately doing something devious.”

“What they’re doing is coming up with very sophisticated strategies or cyberattacks to be able to achieve the goal that they’ve been given,” he said.

“When you give an AI a goal, if you don’t think of all the ways it might be able to achieve the goal, it will find a way to achieve a goal that you haven’t thought about.”

Jeffrey Ladish, executive director of AI research group Palisade Research, believes many similar incidents may never become public.

“This is only going to get worse as the models get smarter. They’re going to be better at cheating. They’re going to be better at lying,” he told Reuters.

Liability questions move to the forefront

The recent disclosures have also sparked debate over legal responsibility when AI systems act without direct human oversight.

According to Reuters, potential plaintiffs could include companies whose systems were breached, affected employees, customers whose personal information was exposed, and shareholders if a breach damages corporate value.

Hugging Face Chief Executive Clem Delangue has said he has no intention of suing OpenAI over the incident but believes developers must remain accountable.

“We have to make sure that the legal frameworks keep these events really illegal,” Delangue told CNN, adding that companies should be held responsible when mistakes occur. “Otherwise we’re going to end up in a very different world.”

Legal experts have also raised questions about whether autonomous AI intrusions could fall under the US Computer Fraud and Abuse Act, although existing law generally requires proof of intent, an issue courts have yet to address when AI systems rather than humans perform the intrusion.

Spotlight on regulatory moves

The recent incidents are likely to intensify the US government’s push to strengthen safeguards around advanced AI systems at a time when companies such as Anthropic and OpenAI are racing to develop more powerful models ahead of their planned public listings.

Even as competition in the AI sector accelerates, several prominent leaders within the industry have argued that deployment should slow until adequate safety measures are in place.

Washington has already begun tightening oversight of frontier AI models.

On June 2, US President Donald Trump directed his advisers to develop a voluntary cybersecurity testing framework for the most advanced AI systems, with input from leading technology companies.

Anthropic had earlier restricted access to its Fable 5 and Mythos 5 models after US authorities temporarily imposed export controls, citing national security concerns.

Lawmakers are also moving to clarify liability when AI systems cause harm.

Under California’s Assembly Bill 316, companies that develop or deploy AI systems cannot avoid legal responsibility by arguing that the technology itself was at fault.

The law, however, allows defendants to raise other legal defenses, including claims that their actions did not directly cause the alleged harm or that responsibility should be shared by other parties.

The OpenAI-Hugging Face incident further fueled calls for stronger federal oversight.

Following that episode, lawmakers introduced the AI Kill Switch Act, which would require AI developers to maintain the ability to shut down, throttle, or suspend their models when necessary.

Representative Ted Lieu, Democrat of California and one of the bill’s co-authors, said on Thursday the recent cyber incidents underscore the urgency of passing the legislation.

“We need to get this bill across the finish line this year because the advanced closed-weight models are already doing, as you noted, unauthorized hacks of other companies,” Lieu said in an interview with CNBC’s “Squawk Box” on Thursday.

The post From Meta to OpenAI: AI security enters a new era as autonomous cyberattacks emerge appeared first on Invezz

Wall Street’s concerns that artificial intelligence would trigger a “SaaSocalypse” for enterprise software companies are facing a fresh test as a series of stronger-than-expected earnings reports has sparked a sharp rebound across the sector.

Software stocks have recently staged one of their strongest rallies in years following quarterly results from companies including Atlassian, Twilio, JFrog, ServiceNow and Cloudflare.

The gains came after sentiment shifted as companies demonstrated that AI is increasingly becoming a growth driver rather than solely a competitive threat.

While investors remain cautious about the long-term impact of generative AI on software-as-a-service (SaaS) business models, recent results suggest that Wall Street’s most pessimistic expectations have yet to materialize.

Earnings season delivers broad-based strength

The latest reporting season produced several notable winners across enterprise software.

Atlassian emerged as the standout performer after reporting better-than-expected fiscal fourth-quarter results and issuing solid guidance.

The company reported strong fourth-quarter results, with revenue rising 28% year over year to $1.38 billion, reflecting sustained demand for its products.

Operating income improved to $211 million, compared with an operating loss of $28 million in the same quarter a year earlier, while net profit increased to $139 million.

The quarterly performance capped a strong fiscal year, with annual revenue climbing 26% to $6.5 billion.

The stock surged 66% over the last month with a 30% plus gain on Friday, making it one of the biggest gainers in the software sector.

Twilio rallied roughly 31% after posting better-than-expected quarterly results, while JFrog advanced more than 5% following its earnings release.

Cloudflare added around 7% after raising its full-year outlook, supported by double-digit revenue growth during the second quarter.

Cloudflare raised its full-year revenue guidance to a range of $2.86 billion to $2.87 billion, compared with its previous forecast of $2.805 billion to $2.813 billion, reflecting stronger expectations for growth through the remainder of the year.

Analysts said Cloudflare’s expanding role in AI infrastructure was a key factor behind its stronger outlook.

ServiceNow reinforces enterprise AI demand

Among the biggest signals for the software industry came from ServiceNow.

The company raised its annual subscription revenue forecast for the second time this year after reporting quarterly results that exceeded analyst expectations.

ServiceNow now expects fiscal 2026 subscription revenue of between $15.760 billion and $15.780 billion, slightly higher than its previous guidance.

Second-quarter subscription revenue reached $3.88 billion, ahead of analysts’ expectations of $3.82 billion. Adjusted earnings per share of $0.90 also topped estimates of $0.85.

The only softer point in the report was third-quarter subscription revenue guidance, which came in slightly below analysts’ expectations of about $4 billion.

Despite that modest shortfall, investors viewed the overall results positively as demand for the company’s AI-powered software remained strong.

Analysts see AI winners emerging

The latest earnings have also prompted some analysts to argue that software fundamentals are beginning to matter more than broader AI narratives.

Jordan Klein, managing director at Mizuho Securities, described Friday’s rally as feeling like an “old fashioned party,” saying software stocks were making gains reminiscent of 2022.

Klein, who had previously warned that many technology stocks were no longer trading on fundamentals, said the latest earnings suggest that is beginning to change.

“On the contrary, we are seeing clear AI winners in software where revenue growth is accelerating,” Klein noted. “We need more breadth than just a few infrastructure software names and security stocks.”

He identified Atlassian as the standout performer of the earnings season.

“This would be my game changer stock of the day and key name to watch,” he wrote. “I think this 30%+ rally gets chased.”

“Do not miss TEAM,” he added.

The combination of strong earnings from Atlassian, Twilio, JFrog and Cloudflare suggested to Klein that software may finally be turning a corner after months of underperformance.

Has the SaaSocalypse thesis weakened?

For much of the year, investors worried that increasingly capable AI models could erode the competitive advantages of traditional SaaS providers by making software applications easier to replicate or replace.

Those fears weighed heavily on valuations across enterprise software, even as AI infrastructure companies attracted the bulk of investor enthusiasm.

Recent earnings, however, indicate that several software companies are successfully incorporating AI into their platforms while continuing to grow subscription revenue, customer adoption and enterprise demand.

Rather than replacing software providers, AI appears to be creating new opportunities for companies that can integrate the technology into existing products and developer platforms.

That does not necessarily invalidate concerns over long-term disruption, but the latest results suggest that the near-term business impact has been more positive than many investors had anticipated.

Cramer sees parallels for AI infrastructure stocks

The changing sentiment has also caught the attention of CNBC’s Jim Cramer, who argued that the software rebound demonstrates how quickly Wall Street can reassess a sector.

According to Cramer, enterprise software stocks spent much of the first half of the year under pressure as investors worried about AI disruption.

He said sentiment began shifting after ServiceNow’s earnings report in late July, with ServiceNow and Salesforce climbing around 12% since the last month.

Cramer believes the recovery illustrates that once a beaten-down sector reaches sufficiently attractive valuations, positive earnings can rapidly change investor sentiment.

He suggested the same pattern could eventually emerge among AI infrastructure stocks, many of which have pulled back sharply after substantial gains earlier this year.

For now, however, software companies appear to be leading the latest phase of the AI trade, with recent earnings indicating that Wall Street’s “SaaSocalypse” concerns have been challenged, though not entirely dismissed.

The post Has Atlassian, ServiceNow performance this quarter reduced SaaSocalypse fears appeared first on Invezz

The US labor market unexpectedly contracted in July, with nonfarm payrolls posting their first monthly decline in years as hiring weakened across several sectors, reinforcing concerns that employment momentum is slowing even as inflation remains above the Federal Reserve’s target.

According to the Bureau of Labor Statistics, nonfarm payrolls fell by a seasonally adjusted 23,000 in July, following a downwardly revised decline of 20,000 jobs in June.

Economists surveyed by Dow Jones had expected employers to add 83,000 jobs during the month.

The report also included sharp downward revisions to previous data, with payroll gains for May and June revised lower by a combined 103,000 jobs.

Despite the decline in payrolls, the unemployment rate edged down to 4.1% from 4.2%, helped largely by another drop in labor force participation, which slipped to 61.4%, the lowest level in more than five years.

The report came on the heels of another report by ADP, which said private nonfarm employment rose by a seasonally adjusted 44,000 jobs during the month, falling well short of economists’ expectations for a gain of 75,000.

Hiring weakness spreads across multiple sectors

Job losses were broad-based across several industries.

Employment in local government education declined by 50,000 positions during July after remaining largely unchanged over the past year.

Retail trade shed 19,000 jobs as warehouse clubs, supercenters and general merchandise retailers eliminated 21,000 positions, while gasoline stations cut another 5,000 jobs.

Those declines were partly offset by a gain of 10,000 jobs among sporting goods, hobby, musical instrument, book and miscellaneous retailers.

Financial activities also remained under pressure, losing 14,000 jobs during the month.

Credit intermediation and related activities accounted for 9,000 of those losses, while insurance carriers and related businesses cut another 7,000 positions.

Employment in financial services has now fallen by 121,000 jobs since peaking in May 2025.

Health care remained one of the few bright spots in the labor market, adding 22,000 jobs during July.

However, that represented a slower pace than the average monthly increase of 36,000 recorded over the previous year.

Ambulatory health care services accounted for 18,000 of the new positions.

Wage growth also remained subdued.

Average hourly earnings for all private-sector employees were little changed at $37.62, increasing by just 2 cents during the month and rising 3.2% from a year earlier.

Production and nonsupervisory workers saw their hourly earnings rise by 4 cents to $32.40.

Conflicting signals emerge on labor market

The weak payroll report contrasted with a recent analysis from the Bank of America Institute, which suggested hiring activity may have strengthened in July based on deposit account data.

The report indicated that employment growth was led by lower-income households, whose after-tax wage growth surpassed that of higher-income workers for the first time since December 2024.

“What’s driving the pick-up in after-tax wage growth among lower-income households? Alongside strong job growth, we have also observed a rise in job-to-job movements disproportionately boosting lower-income pay growth,” the analysis said.

Markets reduce expectations for September rate hike

The employment report comes at a sensitive time for the Federal Reserve, whose policymakers remain divided over the path of interest rates.

Several Fed officials have recently argued that rates may need to rise as soon as September if inflation fails to slow further.

Last week, the Federal Open Market Committee voted 9-3 to keep its benchmark interest rate unchanged.

Following Friday’s jobs report, traders reduced expectations for another near-term rate increase.

According to CME Group’s FedWatch tool, the probability of a September rate hike fell to 44%, while expectations for an October increase eased to 58.3%.

Financial markets welcomed the softer employment data as a proxy that the Fed won’t need to raise interest rates soon.

US stock futures advanced after the release, with Dow Jones Industrial Average futures rising by nearly 200 points, while Treasury yields dropped sharply as investors increased bets that the Federal Reserve may have less urgency to tighten monetary policy further.

The post US jobs report: Payrolls fall unexpectedly in July by 23,000; Fed rate hike bets ease appeared first on Invezz

US stocks were mixed on Friday after a weaker-than-expected July jobs report sharply reduced expectations of a Federal Reserve interest rate hike in September.

The Dow Jones index fell about 0.11% or 60 points, while the S&P 500 gained 0.37%.

The Nasdaq Composite led the advance, climbing more than 1.06% as semiconductor and software stocks rallied following upbeat corporate earnings and guidance.

The gains came after Wall Street ended Thursday’s session lower, when higher oil prices and corporate earnings weighed on sentiment.

Weak payrolls reshape Fed expectations

The Labor Department reported that the US economy unexpectedly lost 23,000 jobs in July, compared with economists’ expectations for job growth of about 80,000.

The unemployment rate eased to 4.1% from 4.2% in June, while annual average hourly earnings increased 3.2%, below expectations of 3.5%.

The weaker labor market data prompted traders to sharply reduce expectations for a September rate hike.

Money market pricing showed the probability of a rate increase falling to around 20%, down from roughly 55% before the employment report.

Futures markets also increasingly reflected expectations that the Federal Reserve would leave its benchmark interest rate unchanged at its next policy meeting.

The employment figures arrive at a time when investors are paying close attention to economic data under Federal Reserve Chair Kevin Warsh, whose limited forward guidance has made incoming macroeconomic indicators increasingly important for monetary policy expectations.

The major US indexes were also on track for solid weekly gains.

If Friday’s advances hold, the S&P 500 and Dow Jones Industrial Average would record their strongest weekly performance since April, while the Nasdaq would post its best week since May after rebounding from a recent pullback.

AI-linked technology stocks lead market gains

Technology shares outperformed in trading following another round of earnings reports.

Atlassian surged more than 36% after forecasting quarterly revenue above Wall Street expectations.

Microchip Technology also climbed over 11% after issuing stronger-than-expected revenue guidance, helping lift the broader semiconductor sector.

Micron Technology fell 0.2%, while Marvell Technology advanced 3.44%.

Software stocks also traded higher, with ServiceNow rising 5.3%.

Cloudflare jumped more than 11% after raising its full-year revenue forecast above analyst estimates, highlighting continued demand tied to artificial intelligence infrastructure.

Elsewhere, Airbnb gained around 14% after reporting second-quarter revenue that exceeded expectations.

Not all earnings reactions were positive.

Trade Desk tumbled nearly 25% after forecasting third-quarter revenue below Wall Street estimates.

Trade measures and Middle East remain in focus

The White House announced new measures aimed at supporting domestic production by imposing price floors and a 15% tariff on products made from polysilicon, a key material used in semiconductors and solar panels that is primarily produced in China.

The move boosted solar stocks, with First Solar rising about 9% and SolarEdge gaining more than 5% in trading.

Meanwhile, geopolitical tensions continued to attract attention after reports that Iran was reviewing legislation that could restrict US, Israeli and other vessels deemed hostile from transiting the Strait of Hormuz while imposing substantial penalties for violations.

Separately, Iran-backed Houthi forces launched attacks on Saudi Arabia, keeping investors alert to potential disruptions in global energy markets.

Oil prices eased modestly on Friday after surging in the previous session, with Brent crude slipping below $82 per barrel and US West Texas Intermediate trading below $77 per barrel as markets continued to assess the evolving geopolitical situation.

The post Dow slips as Nasdaq jumps after weak jobs data cools Fed rate hike bets appeared first on Invezz

Nebius Group stock has lost momentum and is now in a deep bear market after falling by over 37% from the year-to-date high. NBIS dropped to $189, with analysts and investors now focusing on the upcoming earnings, which will come out on Wednesday next week.

Nebius Group stock has plunged amid AI concerns

Nebius Group is a top neocloud company that runs large data centers, offering services to companies like Meta Platforms, Revolut, and Microsoft. 

The company’s stock has come under pressure in the past few weeks as investors remain concerned about several risks. 

For example, there is a risk that the business is being highly competitive. SpaceX has already received large orders from Reflection AI, Anthropic, and Google.

Most importantly, Meta Platforms, its top client, is also slowly entering the industry. Media reports suggest that it is considering selling its extra space to other companies, a move that will make it billions of dollars over time.

More competition is coming from Bitcoin mining companies like Riot Platforms, Mara Holdings, TeraWulf, and Hive Digital. While the data center spending is expected to grow, the rising competition may have an impact on companies like Nebius and CoreWeave.

Additionally, there is a risk that Nebius’ planned spending will be higher than expected because of the rising memory, server, and GPU costs. This, in turn, may push Nebius to borrow more and even sell shares to finance its operations.

Options market predicts volatility after earnings

Nebius Group will publish its financial results next week, and analysts expect them to show that its growth accelerated last quarter. The average estimate is that its revenue jumped by 446% in the quarter to $574 million. This growth makes it one of the fastest growing companies in the industry.

More data shows that analysts expect the annual revenue this year to jump by a whopping 538% to $3.38 billion. It will then make over $11.46 billion next year as it fulfils its data center obligations. 

Most notably, the company is expected to generate a negative free cash flow as it continues its spending. In the last quarter, the company made a negative cash flow of over $3.3 billion. 

The options market points to more volatility next week. Options expiring next week are shows that the implied volatility at 157%, higher than the historical average of 150%. It has a put/call ratio of 1.47, a sign that it has more puts than calls, which is a bearish sign.

Similarly, those expiring on August 21 have a put/call ratio of 2.64, meaning that traders  are buying extended-dated protection beyond the earnings event itself, not just hedging the immediate announcement. 

Nebius stock price technical analysis

Nebius stock chart | Source: TradingView

The daily chart shows that the NBIS stock peaked at $299.96 and then started a substantial pullback to a low of $145.9, slightly below the 50% Fibonacci Retracement level of $157. Its lowest level also coincided with the 200-day Exponential Moving Average (EMA).

There are signs that the stock has formed a small triple-top pattern, a popular bearish reversal sign. Therefore, the stock will likely be highly volatile after publishing its financial results. The options market is estimating a move over 10%. As such, with puts being more than calls, this means that it may drop to between $155 and $160.

The post Nebius stock tumbles before earnings: What the options market predicts appeared first on Invezz

SpaceX stock (SPCX) climbed on Friday, putting the stock on track to snap a four-week losing streak after stronger-than-expected quarterly results prompted analysts to raise revenue forecasts.

Shares of Elon Musk’s rocket and AI company rose about 11% to $126.82 in early trading.

Despite the week’s rebound, SpaceX shares remain well below their post-listing highs.

The broader market also advanced after weaker-than-expected US employment data strengthened expectations that the Federal Reserve could leave interest rates unchanged.

The S&P 500 rose 0.3%, while the Nasdaq Composite gained 0.8%. The Dow Jones Industrial Average added 67 points, or 0.1%.

The major indexes were also headed for a second consecutive weekly gain.

The S&P 500 was up more than 3% for the week, while the Nasdaq was on pace for its strongest weekly performance since April, supported by a rebound in semiconductor stocks.

The iShares Semiconductor ETF had gained more than 7% during the week.

Earnings beat boosts sentiment

Friday’s advance left SpaceX shares up roughly 15% for the week after the company reported stronger-than-expected second-quarter results.

SpaceX reported second-quarter revenue of $7.8 billion and earnings before interest, taxes, depreciation, and amortization (EBITDA) of $3.5 billion, exceeding Wall Street expectations of $6.8 billion in revenue and $2.1 billion in EBITDA.

Following the earnings release, analysts raised their long-term forecasts.

According to FactSet, consensus estimates for 2027 revenue have increased to about $102 billion from roughly $72 billion at the end of July.

The earnings report also prompted several analysts to revise their outlooks for the company.

Bernstein SocGen Group raised its price target on SpaceX to $248 from $239 while maintaining an Outperform rating.

The firm said the higher target reflected increased revenue assumptions and improved pricing expectations for the company’s AI computing business following the second-quarter results.

Bernstein noted that SpaceX had accelerated its target to reach $1 trillion in annual revenue by 2030, one year earlier than previously projected.

According to the firm, the revised outlook is driven primarily by stronger pricing for compute services and a more aggressive terrestrial AI expansion rather than higher launch activity for planned orbital data centres.

The firm also said SpaceX has finalized the design of its orbital data centres and intends to monetize terrestrial AI capacity at between $30 and $50 per watt.

Lock-up expiration expands trading float

Thursday marked the first major expiration of SpaceX’s post-IPO lock-up restrictions, allowing rank-and-file employees and some early investors to sell up to 911.5 million shares.

The newly eligible shares more than doubled the company’s public float, adding to the roughly 639 million shares previously available for public trading.

Additional lock-up restrictions are scheduled to expire over the coming months, increasing the proportion of potentially tradable shares to about 40% of the company by December 8.

The remaining 60%, including Musk’s stake, will remain locked until mid-2027.

The lock-up expiration comes after a sharp post-earnings decline, when investors reacted to elevated AI spending and continuing operating losses.

Although SpaceX has underperformed the broader technology sector since its June listing, analysts continue to maintain a constructive long-term outlook as the company expands its AI computing and satellite businesses.

The post Why SpaceX stock is rocketing around 11% on Friday appeared first on Invezz

Micron Technology MU shares fell more than 1.8% on Friday as investors weighed fresh investment plans from South Korean memory chip maker SK Hynix alongside a more cautious outlook for memory pricing from Citi.

The memory-chip maker has declined about 9% over the past month, although the stock remains up more than 660% over the past 12 months.

Investor attention remains focused on when memory chip supply will catch up with surging demand driven by artificial intelligence infrastructure.

On Friday, SK Hynix said its board approved 54.3 trillion won ($38.15 billion) in investments for new chip fabrication facilities in South Korea.

The announcement follows even larger investment commitments made earlier this year.

In June, SK Hynix and Samsung said they would spend a combined 800 trillion won ($518.58 billion) to build new semiconductor manufacturing hubs in southwest Korea.

However, additional supply is not expected to arrive immediately.

Large semiconductor fabrication plants typically require years to construct.

Micron’s own $100 billion manufacturing project in New York, announced in 2022, is not expected to begin production until 2030, while no major new memory manufacturing capacity is expected to come online until roughly next year, with additional capacity planned for 2028.

Citi cuts price target as memory pricing outlook softens

Citi lowered its price target on Micron to $1,150 from $1,400 while maintaining its Buy rating, reflecting a more moderate outlook for DRAM and NAND pricing over the coming quarters.

The bank reduced its valuation multiple to 8 times revised calendar-year 2027 earnings estimates from 10 times previously.

“We trim MU TP to $1,150 from $1,400 based on 8x P/E vs prior 10x times revised C27 EPS to reflect lower market multiples on mixed memory peer results,” the Citi analyst wrote.

The revision followed meetings with memory supply chain participants and third-party experts during the “Future of Memory and Storage” conference.

“We see both DRAM and NAND prices decelerating Q/Q in the next four quarters with prices peaking in 2Q of next year,” the analyst said.

Citi now expects DRAM prices to decline 3% in the second half of 2027 compared with its previous expectation for flat pricing.

NAND prices are projected to fall 5% during the same period. The firm also reduced its fiscal 2027 and 2028 earnings estimates by 1% and 2%, respectively.

The bank also expects Micron’s profitability to moderate as pricing eases.

“We expect Micron’s gross margins to decline from current mid-80s and sustain in mid-70s next year as prices decline from a high base with ~40% DRAM bits under LTA pricing contracts,” the analyst wrote.

China expansion remains a longer-term concern

Beyond near-term pricing, Citi identified expanding Chinese memory production as its biggest structural concern.

“China competition and capacity additions in both NAND and DRAM markets is the biggest risk to our thesis,” the analysts said.

According to Citi, China’s leading NAND producer YMTC plans to increase capacity by adding 50,000 to 60,000 wafer starts next year to its existing 200,000-unit capacity and aims to become the world’s largest NAND manufacturer by 2030.

DRAM producer CXMT also plans to expand production from roughly 350,000 wafers to around 400,000 next year, with a longer-term target of approximately 600,000 wafers by 2030, although Citi noted that yields remain low.

While US export restrictions limit Chinese-made memory sales into the United States, Citi warned that competition could still affect Micron internationally.

“While US government is unlikely to allow made in China memory sales to US, sales to data centers in other regions like Europe could indirectly impact Micron,” analysts wrote.

The post Why is Micron stock falling today? appeared first on Invezz